Das eBook.de Hörbuch Abo - jederzeit, überall, für nur 7,95 € monatlich!
Jetzt entdecken
mehr erfahren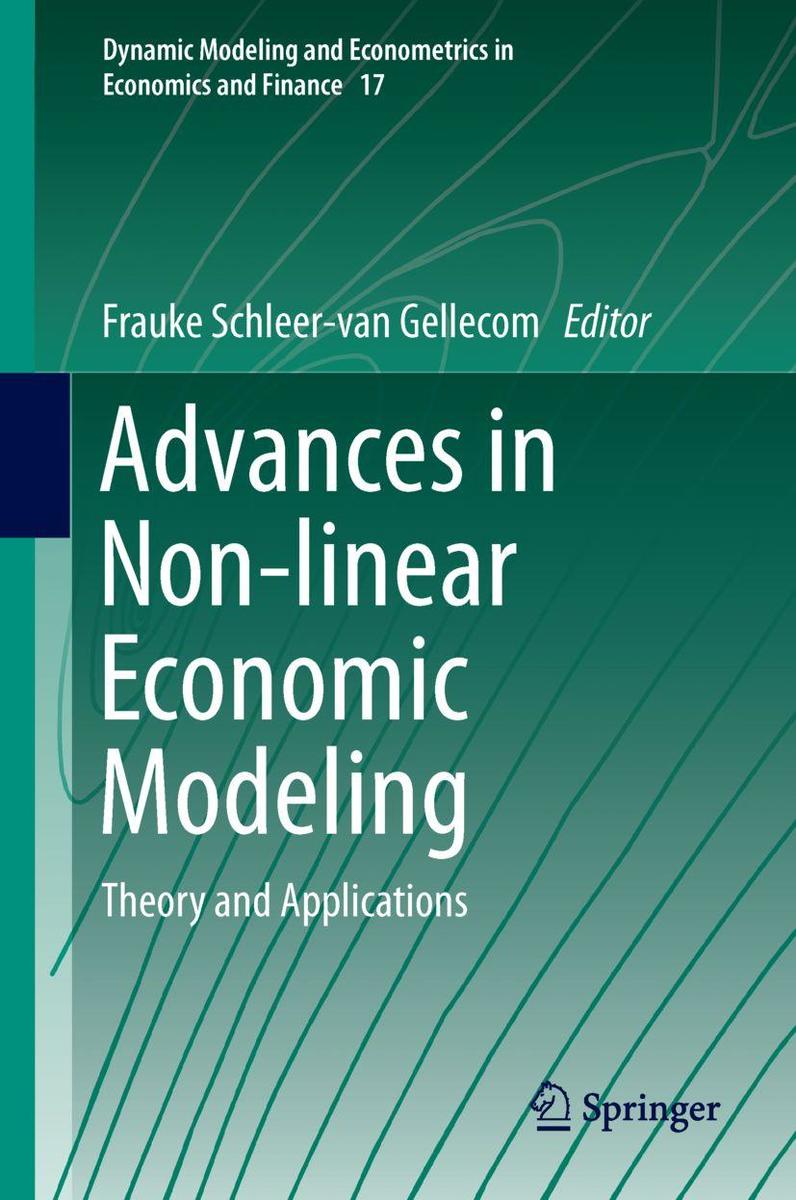
Inhaltsverzeichnis
Non-Linearities Related to the Financial Sector: Mittnik, S. , Semmler, W. : Estimating a Banking-Macro Model Using a Multi-Regime VAR. - Martínez-García, E. : U. S. Business Cycles, Monetary Policy and the External Finance Premium. - Gallegati, M. : Early Warning Signals of Financial Stress: A " Wavelet-Based" Composite Indicators Approach. - Non-Linearities in Other Fields of Research: Sandberg, R. : Least Absolute Deviation Based Unit Root Tests in Smooth Transition Type of Models. - Benati, L. , Lubik, T. A. : The Time-Varying Beveridge Curve. - Charemza, W. , Kharin, Y. , Maevskiy, V. : Bilinear Forecast Risk Assessment for Non-Systematic Inflation: Theory and Evidence. - Karimi, M. , Voia, M. -C. : Currency Crises, Exchange Rate Regimes and Capital Account Liberalization: A Duration Analysis Approach.
Es wurden noch keine Bewertungen abgegeben. Schreiben Sie die erste Bewertung zu "Advances in Non-linear Economic Modeling" und helfen Sie damit anderen bei der Kaufentscheidung.